
Drying the carpet is not the same as drying the building
Water moves down and sideways through a building far further than the visible mark suggests. It runs along the top plate of a wall, down the cavity, under the skirting and out along the underside of a floor, and it does all of that without producing a stain anywhere along the route. A room that looks dry and reads dry at the surface can have a wall base at 40% moisture content behind an entirely normal-looking coat of paint.
Sudden or gradual, and the sublimit behind the word
Florida property policies do not cover mold under the main dwelling limit. They carry it as a separate, capped coverage, usually titled Limited Fungi, Wet or Dry Rot, or Bacteria. Citizens Property Insurance, the state-backed carrier and a large writer across Broward, sets that limit at $10,000 on its HO-3 form, and most carriers sit in similar territory.
Whether that coverage opens at all generally turns on one distinction. Mold that follows a sudden and accidental water event, a burst supply line, a failed appliance, storm damage, is ordinarily within scope. Mold attributed to a slow leak or to months of high humidity is routinely declined as neither sudden nor accidental, and the policy language is written to make that declension straightforward.
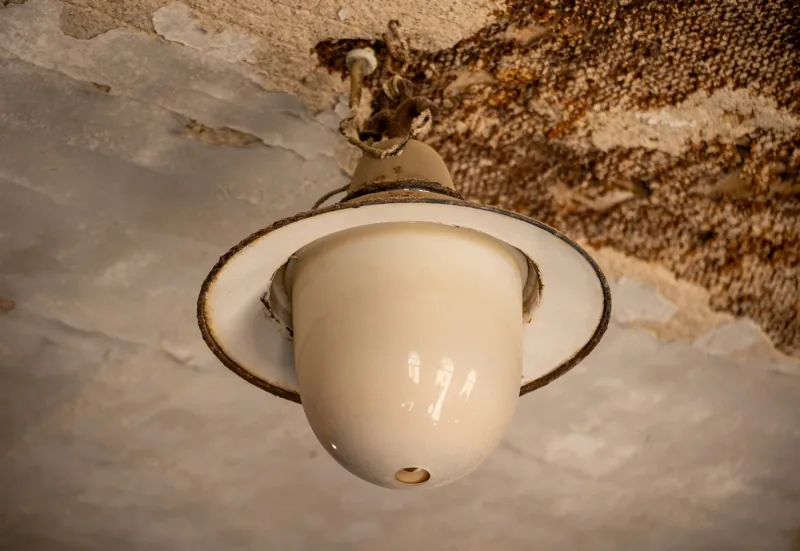
Which of those a building is dealing with is a question of physical evidence, and that evidence has a short life. Moisture gradients across a material, the pattern and number of tide lines in a stain, whether staining has a defined edge or a diffuse one, how far a colony has matured, whether a substrate has begun to delaminate: all of it is altered or destroyed by drying, cleaning and cutting out, which are the first three things anyone does.
So the most useful thing we do on this job is turn up early and write it down. Meter readings across every affected material with the date and time on them, photographs of each stain against a scale, the moisture map of the whole floor plan including the parts that came back dry. We take no position on what your policy should pay, and we are not adjusters. We record the building as it is, in a document somebody who was not there can read.
What the job covers in Fort Lauderdale
What we cover
Mapping how far water travelled and what is still wet after a leak, a burst supply line, a storm or a flood, with the physical evidence of source and timing recorded before drying.
What you get
A dated moisture map, photographs of the staining and material condition that bear on timing, laboratory results, and a scope of work for what has to come out.
Decision point
What the building needs, documented to a standard that survives being argued over by somebody who was not there.